
Yes, selling your Florida home to a cash buyer can stop or resolve an impending foreclosure, as long as the sale closes before the auction date or the certificate of title is issued. Cash buyers typically close in 7 to 14 days, which makes this route faster than most loan modification talks with your servicer. You still have to meet court deadlines, especially the 20-day window to file an answer, and someone needs to coordinate the payoff with your lender before closing day arrives.
TL;DR:
- Selling your home quickly through a cash buyer is most effective if the sale closes within 7 to 14 days, preventing the auction or title issuance.
- You must file an answer within 20 days of service to avoid default judgment and coordinate payoff details with your lender before closing.
- Gathering all financial and property documents early, including proof of funds and clear title, is crucial to meet tight foreclosure timelines.
- Cash offers generally range from 70 to 85 percent of market value, with red flags including upfront fees or lack of a named title company.
- Consulting an attorney and securing written proof of deal terms are essential to avoid legal conflicts and obtain a possible continuance before auction.
Table of Contents
- Quick Checklist: What To Do First When You Consider A Cash Sale
- Florida Foreclosure Timeline: Which Deadlines Actually Matter?
- How Do You Sell Fast To A Cash Buyer, Day By Day?
- How Do You Know If A Cash Offer Is Fair?
- What Should You Verify With An Attorney Before Selling?
- Why A Fast Cash Sale Often Beats Waiting On Lender Talks
- How Sunshine State Buyers Can Help You Move Fast
- Sources
- FAQ
Quick Checklist: What To Do First When You Consider A Cash Sale
Every day matters once a foreclosure complaint lands in your mailbox. Here’s the order that protects your options instead of closing them off:
- File an answer or call a foreclosure attorney within 20 days of being served. Missing this window risks a default judgment, which strips away your leverage to negotiate or sell on your own terms.
- Request an updated payoff statement from your servicer. Pull your deed, title records, property tax statements, HOA ledgers, and insurance documents while you wait.
- Get a fast market-value check. Compare that number against everything owed, mortgage balance, liens, back taxes, HOA dues, to see whether you have real equity or need a short sale instead.
- Reach out to vetted cash buyers and request written offers with firm closing dates. Never pay an upfront fee to get an offer; legitimate buyers don’t charge you to make one.
- Loop in your attorney. Have them handle sale documents and closing logistics alongside the court case.
Pro Tip: Keep a dated folder, physical or digital, of every document you send or receive. If your closing needs to move fast to beat a sale date, having everything organized in one place can save you a full day of scrambling.
If you’re behind on payments and unsure where to start, this step-by-step checklist for homeowners walks through the same priorities in more detail.
Florida Foreclosure Timeline: Which Deadlines Actually Matter?
Florida runs a judicial foreclosure process, meaning your lender has to sue you in court and win a judgment before your home can be sold at auction. That single fact changes everything about your timeline.
- You generally have 20 days to file an answer after being served the complaint, under Florida Statutes Chapter 702.
- An uncontested case can still take several months to over a year to resolve, but a default (failing to answer) accelerates everything toward judgment.
- Once a judgment is entered, the sale is commonly scheduled within roughly 20 to 35 days, unless the court grants a continuance.
Here’s the number that matters most: foreclosure practitioners report that a signed purchase agreement, presented promptly to lender’s counsel, can be enough to persuade them to postpone or cancel a scheduled auction when the sale will pay off the debt in full. Timing that request early, not the week of the sale, is what makes it work.
If the auction is only days away, talk to your attorney about emergency options like a bankruptcy filing, which triggers an automatic stay that temporarily halts the sale, or a motion to continue. These are stopgaps, not solutions, but they can buy the days you need to close a sale properly.
How Do You Sell Fast To A Cash Buyer, Day By Day?
Selling during foreclosure isn’t complicated, but it is sequential. Skip a step and you lose days you don’t have.
Days 0 to 2: Gather documents and get your numbers.
Request the official payoff demand from your servicer. Collect your deed, most recent tax bill, HOA statements if applicable, and any insurance paperwork. At the same time, contact cash buyers and ask each one for a written offer along with proof of funds.
Days 3 to 7: Vet buyers and sign.
Confirm proof of funds and ask which title or escrow company will handle closing, this is a basic legitimacy check most sellers skip. Once you’re comfortable, sign a purchase agreement with a firm closing date. If the buyer’s title company needs to run a title search, provide access promptly so nothing stalls the file.
Days 7 to 14: Clear title and close.
The title company finalizes the payoff amount with your lender, resolves any outstanding liens, and prepares the closing statement. Funds move by wire or through escrow, and the deed gets recorded. At this point, an experienced buyer’s team can coordinate directly with the lender’s attorney to confirm the payoff amount and, when appropriate, request the sale be paused.
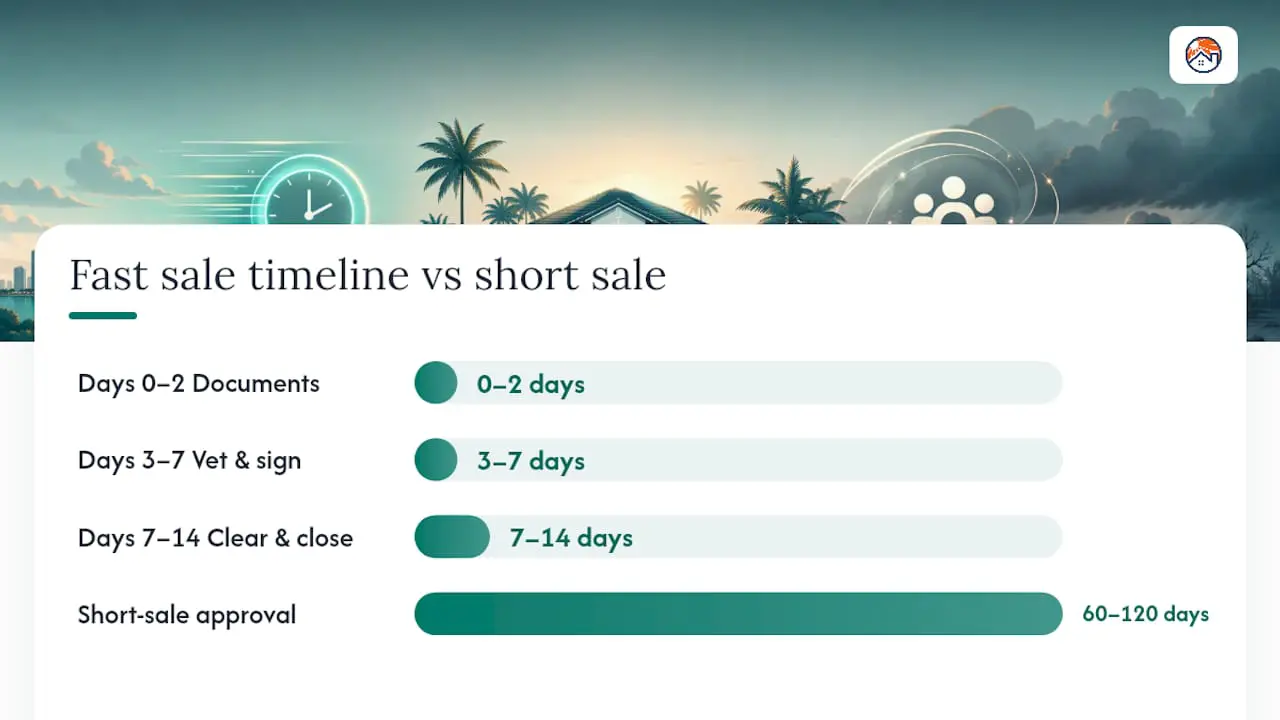
If you owe more than the home is worth, expect a longer road. Short sales require lender approval and typically take 60 to 120 days to finalize, which is why cash buyers willing to work through short sale approval, rather than only buying homes with equity, are worth more to a homeowner racing a court date.
Pro Tip: Ask any cash buyer point blank: “Have you closed a deal on a home in active foreclosure before?” Their answer, and how specific it is, tells you a lot about whether they can actually hit your deadline.
How Do You Know If A Cash Offer Is Fair?
An offer number by itself tells you very little. What matters is your net proceeds, the amount you actually walk away with after every deduction.
- Ask for a written breakdown: offer price minus mortgage payoff, any liens, closing costs, and prorated taxes or HOA dues.
- Understand the tradeoff going in. Cash offers for as-is sales often land in the 70 to 85 percent range of market value, and that discount is the price of speed, certainty, and skipping repairs entirely.
- Watch for red flags: any request for an upfront fee, no named title or escrow company, pressure to sign a deed before closing, or a “sign today or the offer disappears” pitch.
- Before you sign anything, ask for proof of funds, a firm closing date in writing, the title company’s name and contact, and a sample closing statement showing your estimated net.
Pro Tip: If a buyer can’t name their title company or escrow agent within a day of asking, that’s not a paperwork delay, it’s a warning sign.
Curious whether a specific offer holds up? This breakdown of common lowball tactics walks through exactly what a fair offer should look like on paper.
What Should You Verify With An Attorney Before Selling?
A cash sale doesn’t remove the legal case against you, it runs alongside it. A few checkpoints keep the two from colliding:
- Confirm your answer was filed within the 20-day window; this alone can prevent a default judgment that undermines your ability to sell on your terms.
- Ask your attorney to formally notify the court and opposing counsel about the pending sale, and to request a continuance if the closing date and the auction date are too close together.
- Confirm the payoff procedure with your lender’s counsel, and ask whether a deficiency judgment (a court order requiring you to pay the difference if the sale doesn’t fully cover the debt) is possible in your case.
- If the sale is set for days away, discuss emergency remedies like a bankruptcy stay with your attorney before you assume a private sale alone will stop it.
Roughly 20 days is all Florida law gives you to respond once you’re served, which is why this conversation with counsel needs to happen in week one, not week three.
Why A Fast Cash Sale Often Beats Waiting On Lender Talks
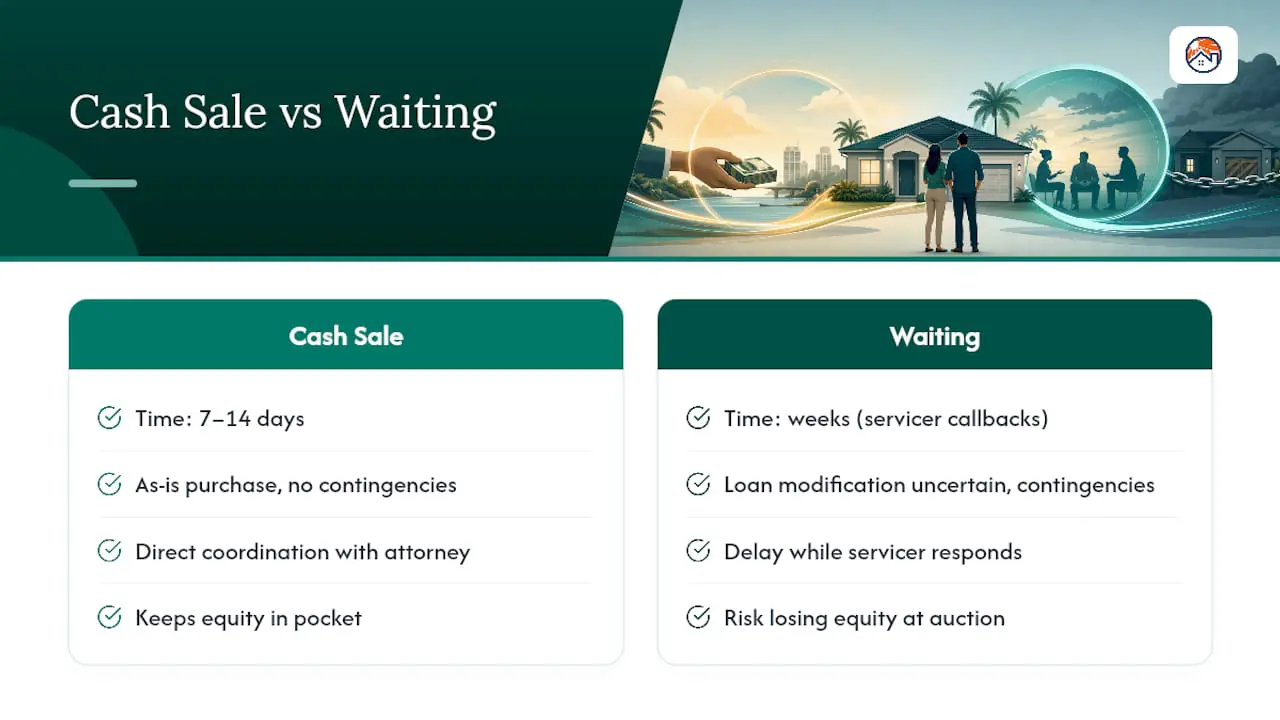
Homeowners spend weeks waiting on servicer callbacks, hoping for a loan modification that may never materialize. Sunshine State Buyers has watched that pattern play out across Florida for years, and the math rarely favors waiting. An A+ BBB rating and a track record of closings inside 7 to 14 days reflect a business built around one job: buying homes as-is, fast, without the contingencies that sink traditional sales. That speed, paired with direct coordination between the buyer’s team and your attorney, is often what keeps equity in your pocket instead of losing it at auction.
None of that replaces legal advice. Always get attorney review before signing anything, and insist on written proof of funds and a firm closing timeline before you commit to any buyer.
— David
How Sunshine State Buyers Can Help You Move Fast
If the deadlines above feel like they’re closing in, you don’t have to navigate them alone. Sunshine State Buyers gives Florida homeowners a direct path to a closed sale in days, not months, buying homes as-is, in any condition, with no repairs, no showings, and no commissions eating into your proceeds.
You get a written cash offer within 24 hours of reaching out, and you pick the closing date, typically 7 to 14 days out, though the timeline flexes if your court date needs faster action. The next step is simple: call for a free, no-obligation consultation, gather the payoff and title documents from the checklist above, and let the team walk you through exactly how the process works from first call to closing table. There’s no pressure and no upfront cost to find out what your home is worth on your timeline, not the court’s.
Sources
- Florida Statutes — Chapter 702 (2026)
- Florida foreclosure process: Homeowner rights and laws — Nolo
- Selling your house as-is during foreclosure in Florida — FL Foreclosure Help
- Q: Can I sell my home before foreclosure? — Justia Answers
This article is general information, not a substitute for advice from a qualified lawyer. Consult a qualified legal professional about your own circumstances before acting on anything here.
FAQ
Can I sell my house after a foreclosure lawsuit is filed?
Yes. You can sell at any point before the sale is finalized, though you still need to answer the complaint within 20 days and coordinate the payoff with your lender before closing.
How fast can a cash sale actually close in Florida?
Most cash buyers, including Sunshine State Buyers, close in 7 to 14 days once a signed agreement and clear title are in place.
Will selling for cash stop a scheduled auction?
It can, if you present a signed purchase contract and proof of closing to your lender’s attorney early enough for them to request a continuance; waiting until days before the sale date makes this far less likely to work.
What if I owe more than my home is worth?
You’ll likely need a short sale, which requires lender approval and can take 60 to 120 days, so start that conversation with your servicer and a cash buyer as early as possible.
Do cash buyers charge fees to make an offer?
No legitimate cash buyer charges you an upfront fee for a written offer; if someone asks for money before closing, treat that as a serious red flag.
Recommended
- Stop Foreclosure Florida: Your Guide to Solutions
- Miami Foreclosure Timeline and Your Options
- Can You Sell Your House During Foreclosure in Miami?
- Cash Offer vs Traditional Sale Miami Explained
This article was produced with AI assistance and reviewed for accuracy. It is provided for general information only and is not professional advice.

Leave a Reply